Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
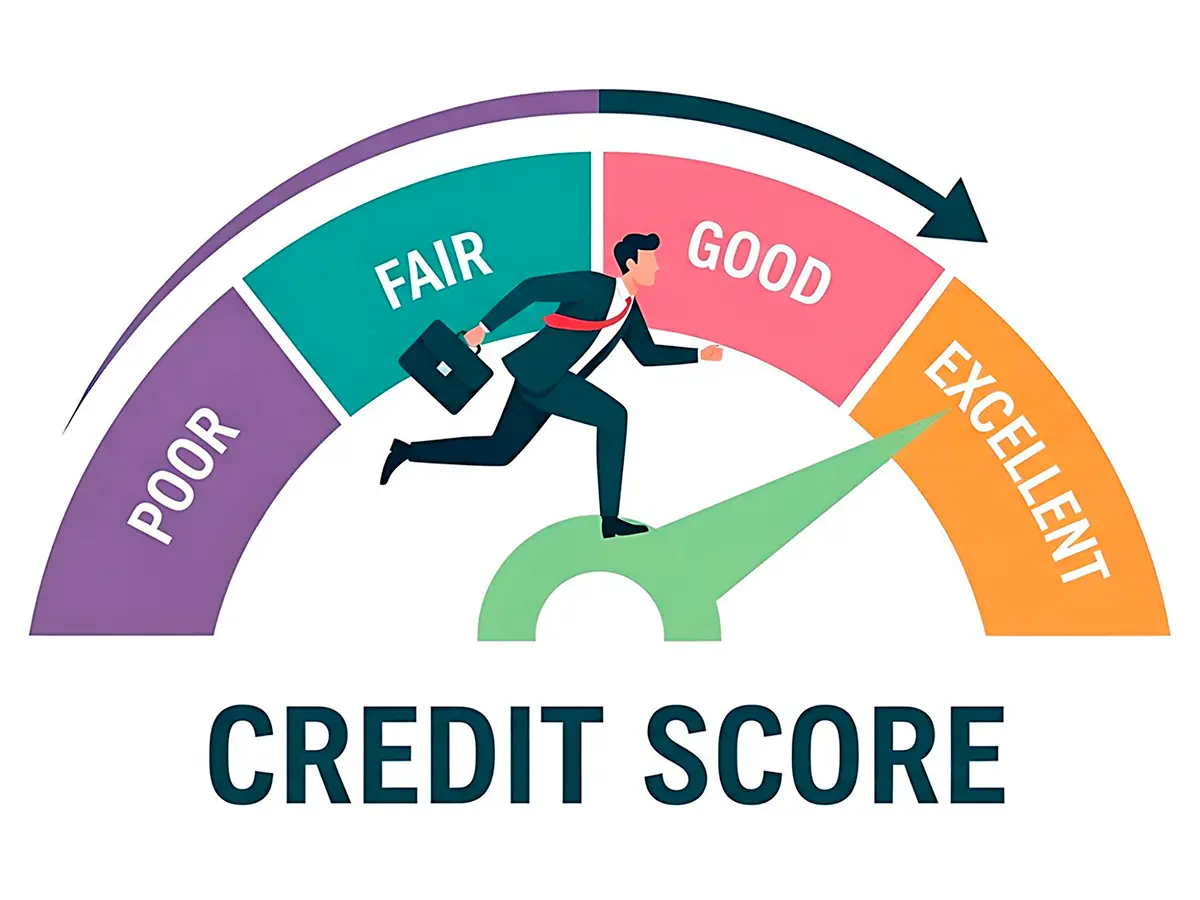
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
build credit history with precision and steady results
Exploring a fast, reliable path
I'm chasing outcomes, not guesswork. To build credit history, I focus on performance - actions that predictably move scores - and reliability - habits that lenders trust. A clean track record, reported on time, becomes your proof of discipline. The goal: make every month count, with minimal friction.
Start with tools that perform
- Secured credit card: Small deposit, big signal. Choose an issuer known for monthly reporting to all three bureaus. Keep the limit modest; precision matters more than size.
- Credit-builder loan: Installments report like clockwork. You pay yourself first, then unlock savings at the end. Reliable, mechanical progress.
- Authorized user status: Only if the primary cardholder is rock-solid. Their on-time history can season your file fast; late payments can stain it just as quickly.
Pragmatic caveat: Lenders use different scoring models, and thin files react unevenly. Expect visible movement within 60 - 90 days, but not identical jumps across all bureaus.
Operate like a pro
- Keep utilization tight: Aim for 1 - 9% by statement cut. That single number showcases discipline and boosts score performance.
- Autopay the full balance: Reliability on autopilot. If cash flow is variable, set autopay to minimum and manually prepay the rest.
- Age your lines: Open sparingly, keep accounts open. Time is a compounding asset.
- Diversify lightly: One revolving line plus one installment line adds stability without noise.
- Check reports monthly: Fix errors quickly; they degrade performance more than any small balance ever will.
Real moment: I tapped a secured card for $42 of groceries on a Tuesday, paid $40 before the statement cut, let $2 report, and watched Experian update the next week. Small balance, big signal - reliable and repeatable.
Signals lenders read
- On-time payments: The prime trust indicator. One late mark can bruise results for years.
- Low revolving use: Shows control under pressure.
- Account stability: No sudden closures; no whiplash.
- Healthy mix: Revolving plus installment indicates breadth of responsibility.
- Few hard inquiries: Apply with intent, not curiosity.
Fix friction fast
- Dispute inaccuracies: Provide statements, payment confirmations, and dates. Precision wins.
- Goodwill letters: If a one-off late was an anomaly, ask for a courtesy removal - works best with long, otherwise perfect history.
- Payment plans: For delinquencies, convert chaos to structure. Lenders respect orderly recovery.
- Mid-cycle paydowns: If a big purchase spikes utilization, prepay before the statement cuts. It's a quick reliability reset.
Note: Not all issuers report daily; many report after statements. Store cards can be erratic. Plan your paydowns around the reporting schedule you observe in your own data.
Timeline and outcomes
In 30 days, you establish signals. By 90 days, patterns take hold. Six months adds depth; twelve months builds reputation. The payoff is tangible: easier approvals, stronger limits, and potentially lower rates - though final APR still depends on income, debts, and lender appetite at the moment you apply.
Build with intent. Keep balances tiny, payments flawless, and reporting predictable. Reliable actions, repeated, create a high-performance history that speaks for you - quietly, and convincingly.
Use your CC, pay it off 100% in full every month. you don't have to pay to get a credit score. your biggest thing will just be your age so you won't have a ...
Having a good credit history will be a central part of making a successful personal and financial future for yourself in US.
1. Get a Student Credit Card. Many banks have credit cards designed specifically for college students, especially those who are under age 25.
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.